Updated October 2026.
London is one of the deepest residential markets in the world, with an established legal system, transparent title registration and a buyer pool drawn from many countries. None of that makes every purchase a good one. For overseas buyers, the costs of buying and holding, the differences between areas and the quality of the specific building matter as much as the city itself.
Understanding the market
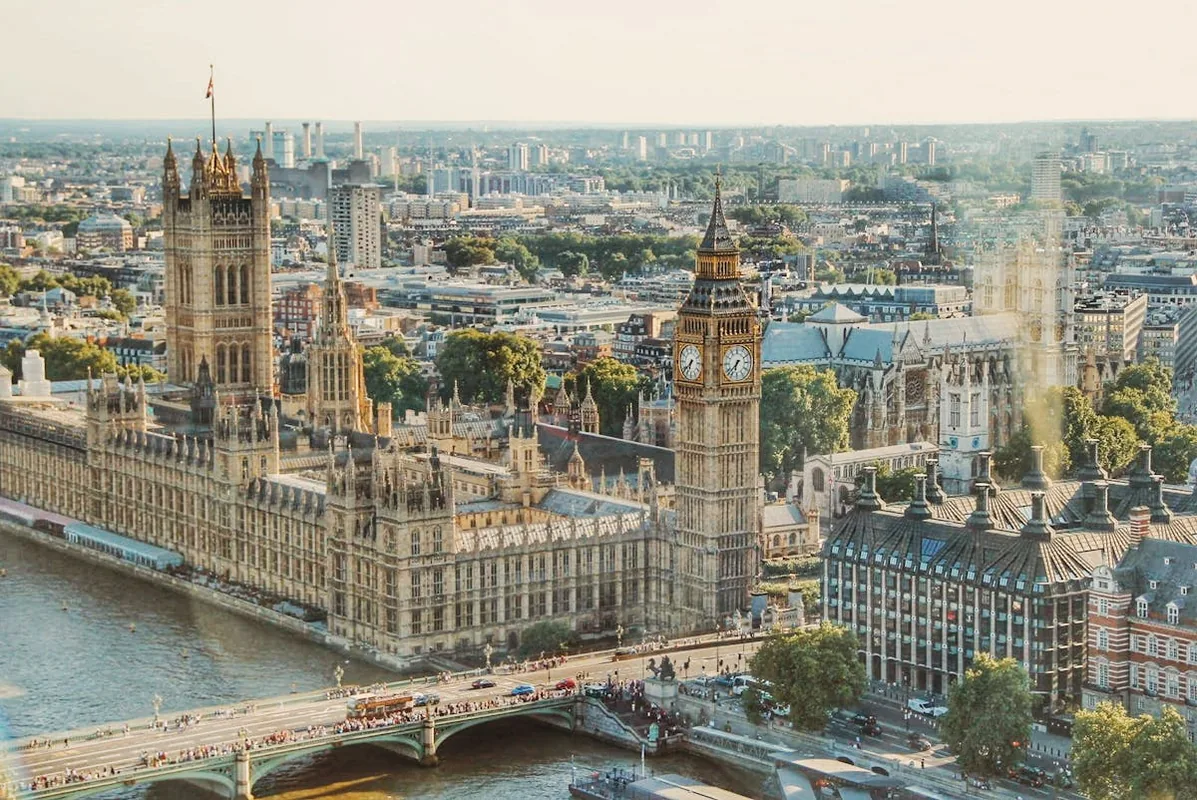
Prime central London — Mayfair, Knightsbridge, Belgravia, Chelsea and the riverside around Westminster — has the highest prices and the most international buyer pool. Income yields there are typically low, and prices have been volatile over the past decade. Prime outer London — areas such as Battersea, Wimbledon, Kingston, Richmond and parts of West London — offers lower entry prices, more family-oriented demand and, in many cases, higher rental yields, but also more new-build competition.
Within any area, the building matters: service charges, leasehold terms, the amount of competing new supply nearby and the depth of the resale market can all make two similar-looking flats very different investments.
Costs to plan for
Stamp Duty Land Tax (SDLT) for residential purchases in England is charged in bands: 0% up to £125,000, 2% to £250,000, 5% to £925,000, 10% to £1.5 million and 12% above (rates in force from 1 April 2025). Buyers who already own residential property anywhere in the world usually pay a 5% higher-rates surcharge on top, and non-UK residents pay a further 2% surcharge. As an illustration, a non-resident who already owns property elsewhere would pay roughly £80,000 on a £750,000 purchase. Your solicitor confirms the exact figure — and rates can change at any Budget.
Beyond SDLT, budget for legal fees, any mortgage costs, and ongoing costs including service charges, ground rent where it applies, council tax when the property is empty, insurance, letting and management fees, and maintenance.
Tax while you own the property
Rental income from UK property is generally taxable in the UK. Non-resident landlords are subject to the Non-Resident Landlord Scheme, under which tax is withheld from rent unless HMRC approves gross payment. Gains on disposal of UK residential property are within UK capital gains tax for non-residents, and UK residential property is within the scope of UK inheritance tax regardless of where the owner lives. The right ownership structure depends on your circumstances — take UK tax advice before you buy.
How CM2 approaches an acquisition
CM2 starts with your mandate — budget, objectives, location, intended use, horizon and risk tolerance — and then assesses opportunities against it on evidence: comparable pricing, rental evidence (labelled as estimates), running costs, supply and exit considerations. You receive a focused shortlist, including what does not fit and what still needs verifying.
CM2 operates on the buyer side while receiving compensation from participating developer partners, including Aldar Properties and London Square. Buyers are not charged a fee by CM2. This article is general information, not legal, tax or financial advice. Figures may be indicative, availability can change and projected yields are not guaranteed.
Request a private consultation or read the step-by-step purchase process.